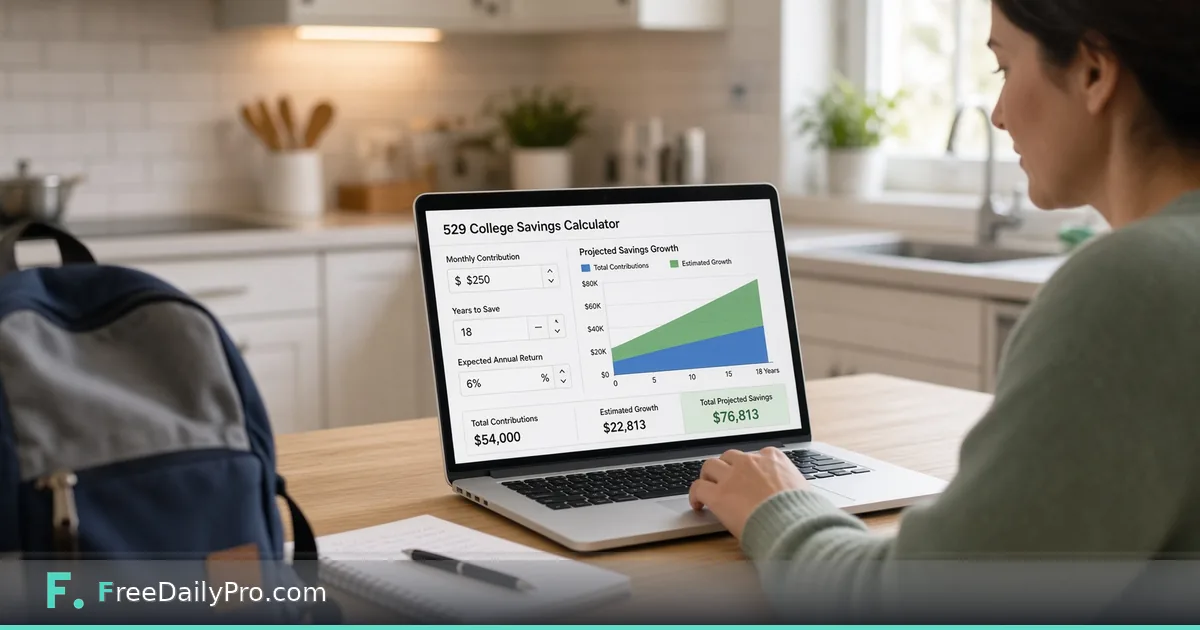
Monthly 529 Savings for a $100,000 Goal: What the Math Says
Work out the fixed monthly deposit for a college goal, see how return and start date change it, and learn what this projection leaves out.
A couple with a 3-year-old have a number in their heads, about $100,000 for four years of college, and a savings account that holds $5,000 today. The question is what they would need to put in each month. College 529 Calculator answers it with four inputs and shows how sensitive the result is to the return you assume.
In short: enter the goal, what you have saved, the years until college and an expected annual return. The tool returns one monthly deposit and the amount your current savings would grow to on their own.

The four fields, in the tool's order
Savings Goal ($) is the amount you want to have on the day the money is needed, not today's price. Current Savings ($) is what is already set aside. Years Until College is a whole number of years, and anything below one is treated as one. Expected Annual Return (%) is a single rate applied every year.
The tool grows your current savings monthly at that rate for the full period, subtracts the result from your goal, and then finds the fixed deposit, made at the end of each month, that closes the remaining gap. Nothing else is in the calculation: no fees, taxes, inflation or changes in deposit size over time.
Worked example: $100,000 in 15 years
Enter 100000 as the goal, 5000 as current savings, 15 years and a 6 percent return. The monthly contribution comes to $301.66. Your existing $5,000 would grow on its own to about $12,270, so the monthly deposits only need to cover the remaining $87,730.
Over 180 months those deposits add up to roughly $54,300 of your own money, and the rest of the goal comes from assumed growth. The proportion is the point: at this return and horizon, a large share of the target depends on markets behaving as assumed.
How much each assumption matters
Change one field at a time and the tool recalculates as you type. With the same goal, savings and 15 years, a 4 percent return needs $369.37 a month, 6 percent needs $301.66, and 8 percent needs $241.20. A 0 percent return, meaning savings that do not grow at all, requires $527.78.
Time moves the answer too. At 6 percent, starting a year later (14 years) raises the deposit to $337.17, and with only 10 years left it is $554.69. Each year of delay costs more than the one before, because early money has the longest to grow. The gap between 4 and 8 percent is $128 a month, which is why a cautious rate is the better way to test your plan.
Steps for a careful run
- Estimate the goal in future dollars, not today's. College Cost Calculator helps, because it applies an annual increase rate and nets out scholarships.
- Enter the current balance of the account or accounts you are counting.
- Enter the years until the first bill is due, rounded down.
- Try three returns: a cautious one, a middling one and an optimistic one. Note all three results.
- Compare the monthly deposit with what your budget can sustain, and decide whether to adjust the goal, the timeline or the deposit.
College Cost Calculator works across multiple years of tuition, room and board, books and fees, so you can plan from a total rather than a rough guess.
The optional First contribution date box shows the calendar side of the plan. With a first contribution on November 1, 2026 and 15 years to go, the last contribution falls on October 1, 2041 and the goal is reached on November 1, 2041. A start day of the 29th to 31st moves to the last day of shorter months. The date only labels the plan: the monthly amount is the same for any date.
What this projection does not do
This is a general projection, not specific to any state's 529 plan. A 529 plan is a US education savings account, and tax benefits, fees and investment choices differ by state and by plan, so check your plan's documents for allowed uses and tax treatment. The tool applies none of that.
It also assumes the same return every year. Real returns rise and fall, and a bad year near the end hurts more than one at the start. The result is an estimate and general information, not tax or investment advice; a financial professional or your plan administrator can speak to your situation.
Using the result to make a decision
Suppose $301.66 a month is more than the budget allows and the family can manage $200. The tool does not solve in reverse, but you can work it out by trial: lower the goal until the monthly figure reads $200, and the goal you end on is what $200 a month would reach under the same assumptions. That tells you how large a gap would be left for scholarships, other savings or borrowing.
If a gap remains, Student Loan Calculator estimates what repaying borrowed money would cost, so you can compare saving a little more now with borrowing later. For a general look at growth with regular deposits, Compound Interest Calculator lets you test a different compounding pattern.
Common mistakes
Entering today's tuition as the goal understates what you will need, because costs usually rise. Typing the return as a decimal, such as 0.06, when the field expects a percentage like 6 gives a wildly different result. Counting an account twice, or including money earmarked for something else, inflates the starting balance.
Another is treating the answer as a promise. The figure is a fixed deposit under a fixed return. A sensible habit is to revisit the plan once a year with the real balance and update the years remaining.
Where it fits
The tool belongs with the other planning tools in the college tools category, and the guide to tools for college students shows how the rest connect. The numbers you type stay in your browser, and each session of calculating can count towards your daily trial uses.
What is the hardest part of planning for college costs in your household: the goal, the timeline or the monthly amount? Tell us on the contact page.