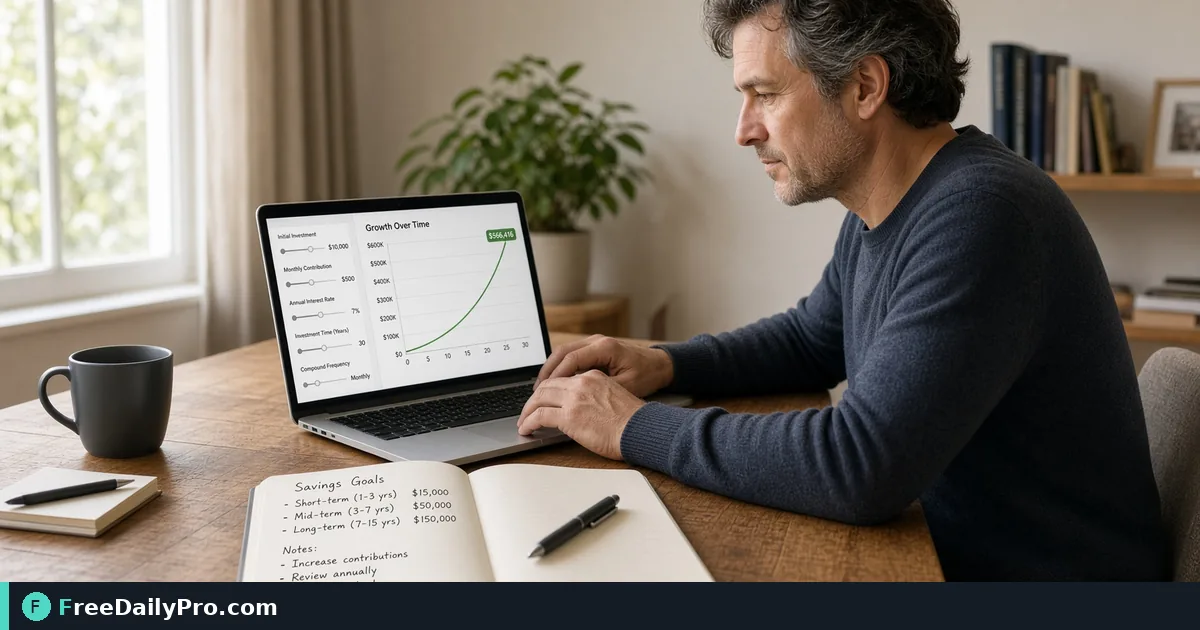
What $12,000 Becomes at 5% Over 8 Years, With and Without Deposits
Model a savings balance with monthly compounding, regular deposits, contribution timing and inflation, then read the year-by-year table.
A savings account advertises 5% and you have $12,000 sitting in a current account doing nothing. Before you move it, you want to know what the balance looks like in eight years, and how much of that comes from your own money versus interest. Compound Interest answers that in one screen.
Enter the starting amount, a monthly deposit, the annual rate, the years, and how often interest compounds. You get contributed money, interest earned, final balance, an optional inflation-adjusted figure and a year-by-year table. The sums happen in your browser as you type.

Run the baseline first: no deposits
Type 12000 as the initial amount, 0 as the monthly contribution, 5 as the annual rate, 8 as the years, and choose Monthly compounding. The result is a final balance of $17,887.03: $12,000 contributed and $5,887.03 of interest. The table shows the path, with about $12,613.94 after year 1 and $14,650.74 after year 4.
Notice the shape. Year 1 earns roughly $614. Year 8 earns about $870 because interest now earns interest. Over eight years the money grew by almost 49%, though the stated rate was only 5% a year.
Add the deposits you can realistically make
Now set Monthly contribution to 200 and leave everything else alone. The final balance becomes $41,435.13 on $31,200 contributed ($12,000 plus 96 deposits of $200), so interest is $10,235.13. The $200 a month added about $23,548 to the final figure, and roughly $4,348 of that is extra interest on the deposits.
The Contributions made menu matters less than people expect. Switching from the end of each period to the start lifts the result to $41,533.25, an extra $98 over eight years, because every deposit earns one more period of interest. If your bank credits your deposit on the first, use the start setting. If you pay in whenever you remember, leave it on end.
Test the rate you will really get
Stated rates are rarely what you keep. Say a fund charges 0.8% a year and you model that by hand: enter 4.2 instead of 5. Keeping the $200 deposits, the final balance drops to $39,554.70, which is $1,880.43 less than at 5%. The tool does not have a fee box, so subtracting the fee from the rate yourself is the honest way to see its drag. It is an approximation, but it is close enough to compare two products.
Do the same for the other direction. Run 3%, 4% and 5% in turn and write the three balances down. A spread you can see on your own numbers is more useful than any rule of thumb.
Does compounding frequency matter?
At 5% and no deposits, annual compounding gives $17,729.47, monthly gives $17,887.03 and daily gives $17,901.41. The gap between annual and daily is about $172 over eight years. That is real but small. The rate and the length of time matter far more, so choose the account first and worry about the compounding schedule last.
What does matter is checking which schedule your account actually uses, and whether the advertised figure is a nominal rate or an annual yield. If the provider quotes a yield, the nominal rate to type here is slightly lower.
The optional Start date box turns the year numbers into dates. If the money starts earning on March 1, 2027, an 8-year run ends on March 1, 2035, the line under the results says so, and each row of the year-by-year table shows the date its year ends. A start on February 29 has its anniversaries on February 28 in years that are not leap years. The date only labels the timeline: the balance and the interest are the same for any date, and a term that is not a whole number of months is rounded to the nearest month for the date only.
Steps in order
- Enter the Initial amount and pick the currency from the dropdown. It changes the symbol and formatting only, not the maths.
- Enter the Monthly contribution. Use 0 if you are investing a lump sum.
- Enter the Annual interest rate as a percentage and the Years, from 1 to 100.
- Choose Compounded: annually, semi-annually, quarterly, monthly or daily.
- Choose whether contributions go in at the start or the end of each period.
- Optionally add an Inflation percentage to see the result in today's money.
- Open Show year-by-year table and read Contributed, Interest and Balance for each year.
Reading the inflation line
Type 2.5 in the Inflation box with the $200 plan. The tool adds a line saying the $41,435.13 is about $34,007.74 in today's money. The nominal balance is what the account shows in eight years. The lower figure is closer to what that money will buy compared with prices now. Use it when judging whether a goal, such as a house deposit, will still be big enough.
Mistakes to watch for
- Typing 0.05 instead of 5 for the rate. The field takes percentages, so a result that barely moves is the clue.
- Forgetting that interest income may be taxable where you live. The calculator shows pre-tax growth.
- Assuming a variable rate stays put. Run a conservative case and a hopeful case and plan around the lower one.
- Counting a one-off bonus as a monthly deposit. Model it by raising the initial amount.
- Reading the result as a promise. It is an estimate from the numbers you entered, not investment advice.
Where to go next
If you contribute on a monthly schedule into funds and want step-up options, the SIP Calculator handles annual increases in the deposit. For a longer horizon aimed at financial independence, try the FIRE Calculator. The wider finance calculators category covers loans and paychecks, and an earlier guide on compound interest and SIP side by side shows how the two differ. Each calculation counts toward your 10 trial usages for the day, so settle the inputs before pressing through variations.
Would you rather compare two savings accounts or plan a savings goal with a deadline? Let us know on the contact page.