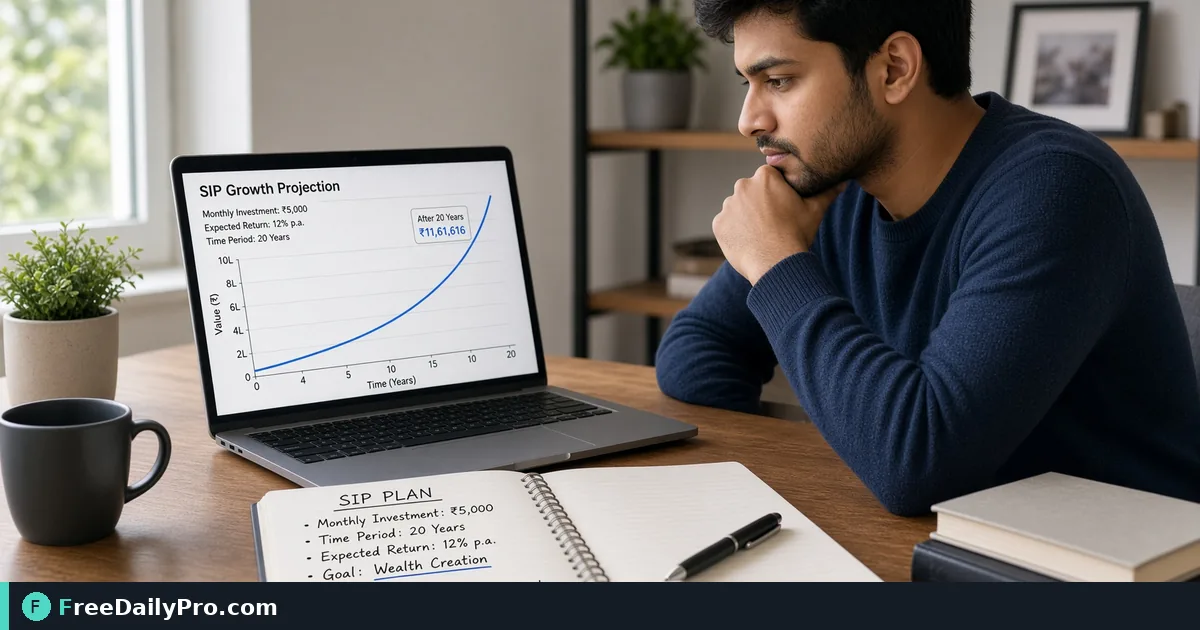
Test a Monthly SIP Plan Against Three Return Rates
Work out what 5,000 a month grows to in 10 years at 8, 10 and 12 percent, then add a step-up, lumpsum and inflation.
Most SIP projections you see online quote one number at one return rate, and that single number quietly becomes the plan. A better habit is to run the same monthly amount at a cautious, a middle and an optimistic rate, and look at the spread. SIP Calculator lets you do that in under a minute, with an optional yearly step-up, a lumpsum and an inflation adjustment.
Quick answer: enter your monthly amount, a return you are only assuming, and the number of years. The tool shows an estimated future value, the total you put in, and the estimated gains, with a year-by-year table you can open. It runs in your browser, and the result is an estimate, not a forecast.
The clip below shows the basic future-value calculation.

A worked case: 5,000 a month for 10 years
Say a 27-year-old plans to put 5,000 rupees into an index fund on the first of every month for ten years. The calculator opens with exactly these defaults: monthly 5,000, return 12 percent, period 10 years, currency INR. The invested amount is 5,000 x 120 = 600,000 whatever the return, so only the gains change.
Here is what the tool's own formula gives at three assumed rates:
| Assumed return | Estimated future value | Estimated gains |
|---|---|---|
| 8% | 920,828 | 320,828 |
| 10% | 1,032,760 | 432,760 |
| 12% | 1,161,695 | 561,695 |
Four points of return move the end value by about 240,000, which is 40 percent of everything the person actually contributed. That spread is the honest answer to "how much will I have": somewhere in a band, depending on a number nobody can know in advance. In INR the tool also prints the figure in lakh and crore, so 1,161,695 shows as about 11.62 lakh.
Using the controls in order
- Pick the currency from the list next to the monthly field. The tool offers USD, EUR, GBP, INR, CAD, AUD, JPY, SGD, AED and ZAR. Only INR gets Indian digit grouping and the lakh and crore line.
- Type the monthly investment. Zero is allowed, which is handy if you only want to see what a lumpsum does.
- Enter the expected annual return. The tool accepts 0 to 100 percent and shows a red message outside that range.
- Enter the period in years, from 1 up to 60.
- Optionally set a yearly step-up. A step-up of 10 means the instalment is multiplied by 1.10 once for every completed year, so year two pays 5,500 a month.
- Optionally add a lumpsum that sits in from month one, and an inflation rate.
- Press "Show year-by-year table" to see contributed amount, interest and balance at the end of each year.
The conventions matter if you compare with a bank or fund app. Each instalment is assumed to go in at the start of the month, and the monthly rate is simply the annual rate divided by 12. A provider that uses a different compounding rule, or invests on the 5th of the month, will show a slightly different figure.
What a step-up, a lumpsum and inflation each change
Keep the base case at 12 percent and change one thing at a time. With a 10 percent yearly step-up, the final value rises from 1,161,695 to about 1,687,163, while the amount invested rises from 600,000 to about 956,245. You paid roughly 356,000 more, and ended with roughly 525,000 more. A step-up is usually easier on a budget than a bigger starting instalment, because it follows a salary that is also rising.
A starting lumpsum of 100,000 changes the result to about 1,491,734 with 700,000 invested. Notice that the lumpsum earns for all ten years, so it grows to about 330,000 by itself at 12 percent, more than three times its size.
The inflation box does not alter the nominal figure. It adds a line, "in today's money". At 6 percent inflation, 1,161,695 in ten years is worth about 648,685 in today's purchasing power. That is barely above the 600,000 invested, and it is the number to use if your goal is a fixed shopping list, such as a deposit, a course fee or a car.
Reading the year-by-year table
Open the table and look at the interest column rather than only the final balance. In the base case the year-1 balance is about 64,047 on 60,000 contributed, so interest is only about 4,047. By year 5 the balance is about 412,432 on 300,000 contributed. By year 10 the interest portion, about 561,695, is nearly as large as the whole contribution. Growth is back-loaded, which is the practical reason to avoid stopping early. Stretching the same plan to 15 years at 12 percent gives about 2,522,880 on 900,000 invested.
The optional First contribution date box puts calendar dates on the plan. If your first instalment is on November 1, 2026, a 10-year plan has its last contribution on October 1, 2036, the maturity value is the value as at November 1, 2036, and the first row of the table reads Nov 2026 to Oct 2027 instead of a bare year number. A start day of the 29th to 31st moves to the last day of shorter months, so a plan that starts on January 31 has its second instalment on February 28. The date only labels the plan: the future value, the invested amount and the gains are the same whatever date you enter.
Mistakes that distort the answer
- Treating the return field as a prediction. It is a constant you choose; real markets move up and down and can lose money.
- Comparing nominal and real values. A target of 1,000,000 in ten years does not buy what 1,000,000 buys today.
- Forgetting costs. Fund expense ratios, taxes and exit charges are not modelled, so subtract your own estimate from the return you enter.
- Using the tool for a loan. A SIP calculator grows money. For borrowing, use the Mortgage Calculator instead, or the Loan Calculator.
- Entering a monthly figure you cannot sustain. Check what is left after tax first with the Paycheck Calculator.
When another tool fits better
For a one-time deposit with no monthly top-ups, Compound Interest is the cleaner fit, and our guide to compound interest and SIP calculators compares the two. If your real question is "when can I stop working", try the FIRE Calculator or browse the finance calculators category. Trial uses are 10 a day, and each run is cheap, so testing five or six rate and step-up combinations is easy.
This page gives general information and an illustration of arithmetic. It is not investment advice, and it does not know your tax position.
Take it away
Write down three numbers before you leave: the monthly amount, the rate you would be happy with and the rate you would be disappointed by. Run both in SIP Calculator, save the two end values, and judge the plan on the lower one.
Would you like a side-by-side guide for a step-up SIP against a bigger starting instalment, or one on goals priced in inflation-adjusted terms? Tell us on the contact page.